Credit Utilization Ratio Explained: Why Maxed-Out Cards Hurt Home Loan Eligibility
High credit-card utilization can affect your CIBIL Score and may influence how lenders assess your home loan application. Learn what to do before you apply.

High credit-card utilization can affect your CIBIL Score and may influence how lenders assess your home loan application. Learn what to do before you apply.
Hard and soft credit enquiries affect your CIBIL profile differently. Learn what happens when lenders check your report and how to protect your score before a home loan.
A higher CIBIL Score can improve your chances of competitive home loan terms. Compare 650, 750 and 800 scores and understand what really affects your rate.
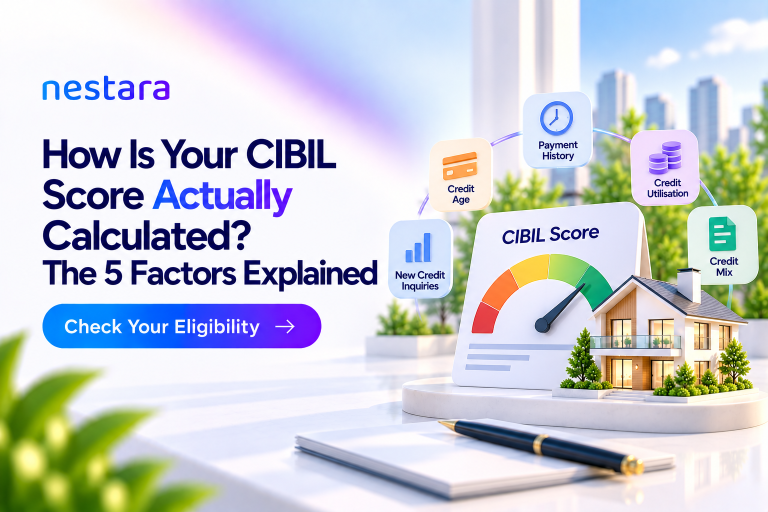
Your CIBIL Score reflects your credit behaviour, not a single number or formula. Learn the 5 key factors that can influence your score before applying for a home loan.
Your credit score can influence the home loan rate you receive. Learn how CIBIL score, repayment history and other factors affect your interest rate and EMI.
The RBI has raised the repo rate to 5.50%. Learn how the 25-bps hike can affect floating home loans, EMIs, tenure and borrowing costs.
Compare 2026 home loan rates across public banks, private banks and NBFCs, and learn how to compare personalised rates, EMI, fees and total interest.
Home loan settlement and foreclosure have different credit implications. Learn how “settled” and “closed” statuses can affect future borrowing and balance transfers.
Learn how to calculate the break-even period on a home loan balance transfer using your rate, outstanding balance, savings and transfer costs.
A lower home loan rate can reduce your EMI and total interest. Learn how to negotiate with your existing bank and when to compare a balance transfer.